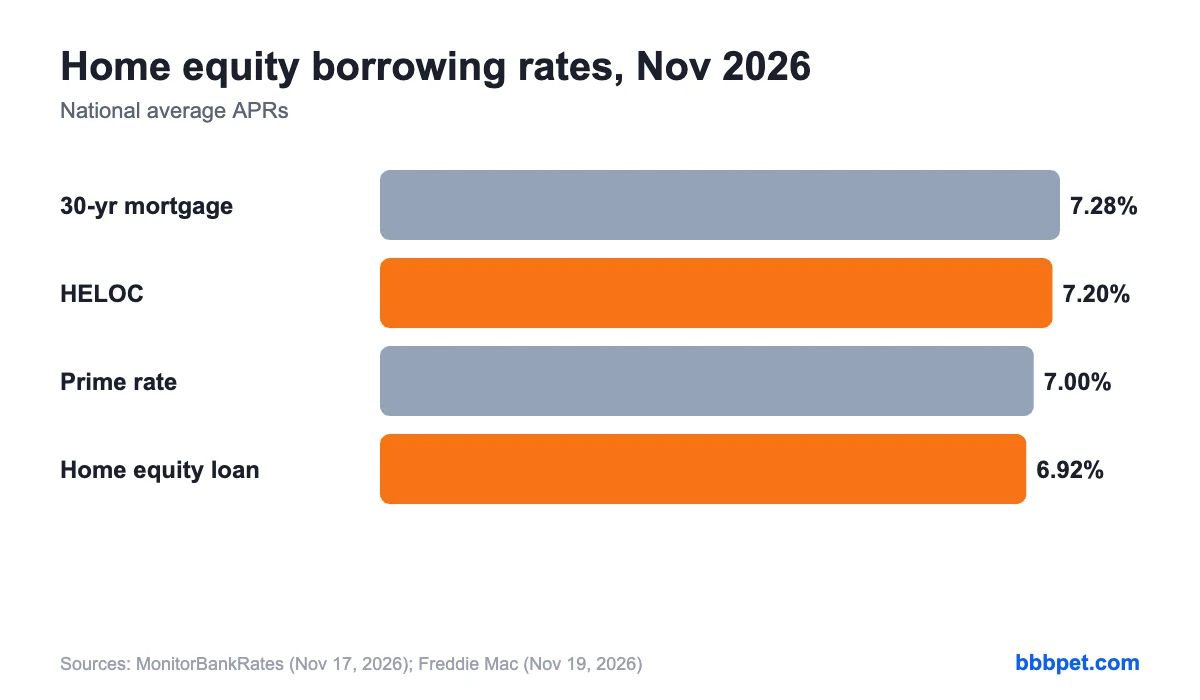
Quick answer: A HELOC is best for ongoing or uncertain costs, a home equity loan is best for one large expense with a fixed payment, and a cash-out refinance mainly makes sense if it doesn’t raise the rate on your existing mortgage. As of November 17, 2026, the average HELOC rate is about 7.20% APR and the average home equity loan rate about 6.92%, according to MonitorBankRates’ survey of more than 1,000 institutions. The prime rate sits at 7.00%.
- Most lenders let you borrow up to 80%–85% of your home’s value, minus what you owe.
- HELOCs are variable and follow the prime rate; home equity loans are usually fixed.
- With 30-year mortgage rates above 7%, a cash-out refi can be costly if your current rate is lower.
- Your home is the collateral for all three — missed payments can lead to foreclosure.
Side-by-side comparison
| HELOC | Home equity loan | Cash-out refinance | |
|---|---|---|---|
| How you get money | Credit line, draw as needed | Lump sum | Lump sum, replaces your mortgage |
| Rate type | Usually variable | Usually fixed | Fixed or adjustable |
| Avg rate (Nov 2026) | ~7.20% APR | ~6.92% APR | Near 30-yr mortgage rates (7%+) |
| Closing costs | Low or none | Low to moderate | Typically 2%–5% of the loan |
| Keeps your current mortgage? | Yes | Yes | No |
| Best for | Renovations in stages, emergency fund | One big project, debt consolidation | Borrowers whose current rate is near or above today’s rates |
How much can you borrow?
Lenders typically cap your combined loan-to-value (CLTV) at 80%–85%. Example: your home is worth $400,000 and you owe $220,000.
- 85% of $400,000 = $340,000
- $340,000 − $220,000 owed = up to $120,000 available
Your credit score (usually 680+, with the best rates at 740+), income and debt-to-income ratio (generally under 43%) also determine how much you’ll be approved for.
What payments look like on $50,000
| Option | Rate used | Estimated monthly payment |
|---|---|---|
| HELOC, interest-only draw period | 7.20% | About $300 |
| Home equity loan, 10-year term | 6.92% | About $578 |
The HELOC payment is lower during the draw period because you’re only paying interest. Once repayment starts (often after 10 years), the payment jumps because you begin repaying principal — and the rate can change with prime.
HELOC: pros and cons
Pros: borrow only what you need, pay interest only on what you use, low closing costs, reusable credit line.
Cons: variable rate, payment shock when repayment begins, lender can freeze or reduce the line if home values fall, and introductory “teaser” rates may reset higher.
Home equity loan: pros and cons
Pros: fixed rate and payment, predictable payoff date, often lower rate than a HELOC right now.
Cons: you pay interest on the full amount from day one, and you can’t re-borrow without a new loan.
Cash-out refinance: pros and cons
Pros: one single payment, can be cheapest if today’s rate is close to or below your current mortgage rate.
Cons: you give up your existing rate on the whole balance, higher closing costs, and you may restart a 30-year term. If your current mortgage is at 3%–5%, a cash-out refi at 7%+ usually costs far more than a HELOC or home equity loan.
Is the interest tax-deductible?
Under IRS rules, interest on home equity debt can be deductible only if you itemize and the money is used to buy, build or substantially improve the home that secures the loan, within the overall mortgage-debt limits. Using it for credit cards or a car doesn’t qualify. Check IRS Publication 936 or a tax professional.
How to get the best home equity rate
- Compare at least three lenders, including a local credit union.
- Ask whether the rate is introductory and what it adjusts to.
- Look for rate discounts for autopay or existing customers.
- Keep your CLTV low — borrowing less often means a better rate.
- Check for annual fees, inactivity fees and early-closure fees on HELOCs.
Frequently asked questions
Which is cheaper right now, a HELOC or a home equity loan?
In November 2026 surveys, average home equity loan rates are slightly lower than HELOC rates. But a HELOC can cost less overall if you only draw part of the line.
Does a HELOC hurt your credit?
Applying causes a hard inquiry, and a large balance can raise your utilization. On-time payments help your score over time.
How long does it take to get a HELOC?
Typically two to six weeks, depending on the appraisal and lender. Some online lenders are faster.
This article is for general information only and is not financial or tax advice. Rates are national averages and change frequently; speak with licensed lenders and a tax professional about your situation.